Section 1446 Withholding: What a US LLC Taxed as a Partnership Owes for Its Foreign Partners
Section 1446(a) withholding explained for a US LLC with foreign partners - when it applies (effectively connected income), the 37% and 21% rates, quarterly installments, Forms 8804, 8805 and 8813, the W-8 each partner gives, and section 1446(f) on transfers.
 Written by Amel Ouchene, IRS PTIN holderLast updated Not legal or tax advice6 min read
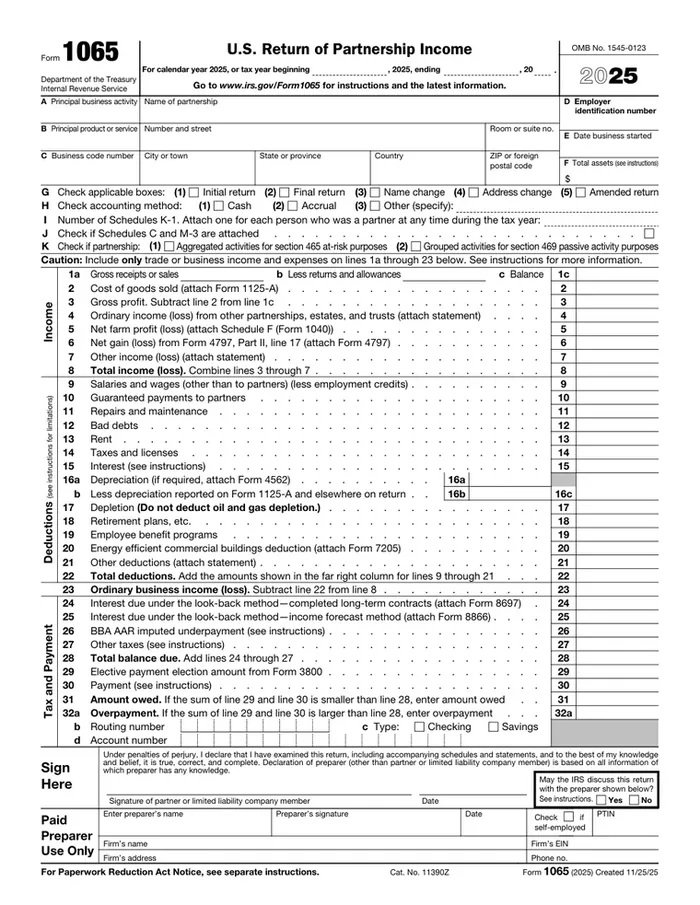
A US LLC with two or more owners is, by default, taxed as a partnership. If one of those owners is a foreign person and the LLC has income effectively connected with a US trade or business, the LLC itself may have to pay a withholding tax on that partner's share of the income. That is section 1446(a) of the Internal Revenue Code. This guide explains when it applies, how much, when it is paid and which forms go with it. The rules come from IRS Publication 515 (2026), section "Partnership Withholding on Effectively Connected Taxable Income (ECTI)".
In short:
- Who: a partnership, "foreign or domestic", that has income effectively connected with a US trade or business must pay a withholding tax on the effectively connected taxable income (ECTI) allocable to its foreign partners.
- Not on other income: the tax "does not apply to income that is not effectively connected with the partnership's U.S. trade or business"; that income may fall under other withholding rules.
- Rate: 37% for noncorporate partners and 21% for corporate partners.
- When: installments by the 15th day of the 4th, 6th, 9th and 12th months of the partnership's tax year, whether or not money is distributed.
- Forms: 8813 (payments), 8804 (annual return, due the 15th day of the 3rd month after year end) and 8805 (statement to each foreign partner).
When section 1446(a) applies
Two conditions together:
- The partnership has effectively connected income, meaning income connected with a US trade or business. Whether an LLC run from abroad has one depends on the facts: people, offices or dependent agents in the United States, for example. Our guide on what a nonresident alien is taxed on explains the difference between effectively connected income and other US income.
- At least one partner is foreign. Publication 515 lists a nonresident alien individual, a foreign corporation, a foreign partnership, a foreign estate or trust, a foreign tax-exempt organization or a foreign government.
If the LLC has no effectively connected income, section 1446(a) does not apply to it, even with foreign partners. The Form 1065 asks about it too: Schedule B, question 14, asks whether the partnership had any foreign partners for purposes of section 1446(a) at any time during the tax year, and the instructions add that a partnership with effectively connected income and foreign partners "may be required to withhold" under section 1446(a) and file Forms 8804, 8805 and 8813.
Who is a foreign partner: the W-8 or W-9 each partner gives
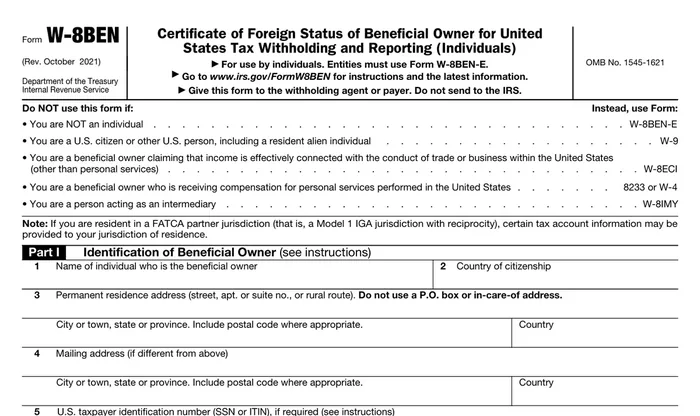
The partnership decides on the basis of each partner's form. A US partner gives a Form W-9. Publication 515 adds a rule that matters: "If a partnership does not receive a Form W-9 (or similar documentation), the partnership must presume that the partner is a foreign person."
| The partner is | Form given to the partnership |
|---|---|
| A nonresident alien individual | W-8BEN |
| A foreign corporation | W-8BEN-E |
| A foreign partnership | W-8IMY |
| A foreign tax-exempt organization or a foreign government | W-8EXP |
A W-8 already given for other withholding purposes can be used for section 1446(a) if it meets the requirements. Our W-8 forms guide explains each form.
How much: 37% or 21%
The withholding applies to the foreign partner's share of the partnership's ECTI for the year. Publication 515: "The withholding tax rate on a partner's share of ECTI is 37% for noncorporate partners and 21% for corporate partners."
The base can be reduced by the partner's share of the related deductions and by treaty benefits on that income. A partner can also certify partner-level deductions and losses on Form 8804-C. If the partner's investment in the partnership is its only activity producing effectively connected income and the section 1446 tax is less than $1,000, no withholding is required, provided the partner gives the partnership a Form 8804-C.
When it is paid, and the three forms
This section is the short version. For who signs, where to mail each form, the Form 8805 copies and the mistakes to avoid, read our guide to Forms 8804, 8805 and 8813.
- Installments (Form 8813). The partnership pays "by the 15th day of the 4th, 6th, 9th, and 12th months of its tax year", for a calendar year April 15, June 15, September 15 and December 15. The installments are due "whether or not distributions are made". Form 8804-W helps compute them.
- Notice to partners. In most cases the partnership must tell each foreign partner of the tax withheld for them within 10 days of the installment date. No particular form is required.
- Annual return (Form 8804). Due by the 15th day of the 3rd month after the end of the tax year, so March 15 for a calendar year, the same date as Form 1065. Form 7004 extends the filing date, not the payment.
- Statement to each partner (Form 8805). Sent to each foreign partner for whom tax was withheld or whose Form 8804-C was considered. It must show the partner's US taxpayer number, so a partner without one may need an ITIN.
The foreign partner then reports the income on their own US return (Form 1040-NR for an individual) and claims the tax withheld. A partnership that "must pay the withholding tax but fails to do so may be liable for the payment of the tax and any penalties and interest."
Section 1446(f): selling an interest in the partnership
Section 1446(f) is a separate rule. When a foreign partner sells or transfers an interest in a partnership engaged in a US trade or business, the buyer may have to withhold on the amount realized. If a foreign owner sells or transfers its interest, or receives a distribution that produces gain, check this rule first; the transferee (the buyer, or the partnership itself for a distribution) generally withholds 10% of the amount realized. Publication 515 has a dedicated section, "Section 1446(f) Withholding".
How Melya helps
Melya prepares the Form 1065 with each partner's K-1, K-2 and K-3 ($599 for up to 2 partners, $99 per additional partner), and the Multi-Founder Partnership bundle ($749 for 2 partners) for LLCs with two or more foreign owners. Whether section 1446 applies to your LLC is part of that review. Forms 8804, 8805 and 8813 are not part of our fixed-price list. Melya signs as paid preparer; it does not represent clients before the IRS and does not advise on the tax rules of your country of residence.
Related reading: Form 1042-S explained for foreign owners · The Schedule K-1 for a non-resident partner
Frequently asked questions
Does every US LLC with a foreign partner withhold under section 1446?
No. Only if the partnership has income effectively connected with a US trade or business. Without it, section 1446(a) does not apply.
Is the withholding paid only when the partners take money out?
No. The installments are due during the year "whether or not distributions are made".
What rate applies to a foreign individual partner?
37%, the rate for noncorporate partners. A corporate partner is withheld at 21%.
When is Form 8804 due?
By the 15th day of the 3rd month after the partnership's year end, so March 15 for a calendar year. Form 7004 gives more time to file, not to pay.
Does the foreign partner still file a US return?
The partner reports the income and claims the tax withheld on their own US return; the withholding is a prepayment, not the final tax.
Sources
- IRS, Publication 515 (2026), Withholding of Tax on Nonresident Aliens and Foreign Entities: Partnership Withholding on ECTI (who must withhold, Chart D, rates, installments, Forms 8804, 8805, 8813, 8804-C), Section 1446(f) Withholding.
- IRS, Instructions for Form 1065: Schedule B, question 14.
- IRS, About Form 8804, Annual Return for Partnership Withholding Tax (Section 1446).
- IRS, Instructions for Form W-8BEN: documentation of foreign partners.
Keep reading
Schedule K-1 for a Non-Resident Partner in a US LLC: What Form 1065 Means for You
A US LLC with several members, one of them non-resident, files Form 1065 and a Schedule K-1 for each partner. What a foreign partner receives, the role of the ITIN and the W-8BEN, section 1446 withholding, and the March 15 deadline.
Read the guideMulti-Member LLC With Foreign Owners: Form 1065 or Form 5472?
Your US LLC has two or more foreign owners. It files Form 1065 and a Schedule K-1 for each partner, not Form 5472, unless it elected to be taxed as a corporation. Deadlines, penalties, and the trap for partners without an SSN or ITIN.
Read the guideW-8 Forms: Which One Do You Need? W-8BEN, W-8BEN-E, W-8ECI, W-8EXP, W-8IMY
What a W-8 form is, the five forms in the family and who signs each one, how long a W-8 stays valid, what the owner of a US LLC gives, and what happens when a US payer pays a foreign contractor without a W-8BEN.
Read the guideThis article is general information about US tax rules for foreign-owned LLCs, not advice for your specific situation. Rules change; check the date above and ask before you file.