For French and Swiss accountants: your client owns a US LLC, we handle the US filings
Your client owns a US LLC and your firm does not file in the US. What the US requires every year (Form 5472, pro forma 1120, sometimes a 1040-NR), and how Melya delivers one file you can use.
 Amel Ouchene, US tax preparer (IRS PTIN holder). October 24, 2026, 3 min read
More and more clients of French and Swiss accounting firms own a US LLC: an online shop, a consulting activity, a software product. The French or Swiss side is your work. The US side is not, and it comes with a penalty if it is missed. This page explains what the United States expects, and how we work with you so that your client is covered without your firm learning US procedure.
In short:
- Every year, the LLC may have to file Form 5472 with a pro forma Form 1120, even if it owes no US tax. The penalty for a missing form is $25,000, and the form cannot be e-filed.
- The owner may also have to file a Form 1040-NR, mainly if the LLC is engaged in a US trade or business or if there is US-source income on which not all the tax was withheld.
- We prepare these US filings for your client, and a file for you: the LLC's figures in euros or Swiss francs and the list of the LLC's bank accounts.
- We do not give French or Swiss tax advice. What your client declares at home stays your decision.
What the US expects each year
A single-member US LLC owned by a foreign person is treated by the IRS as a disregarded entity. It pays no US corporate income tax, but it must still report to the IRS.
- Form 5472 and a pro forma Form 1120. The LLC files them when it had a reportable transaction with its owner, and money the owner put in or took out counts. They are due on April 15 for a calendar-year LLC, or October 15 with a Form 7004 extension. They go by fax or mail. Our line-by-line guide shows every box, and the glossary entry gives the rule and the penalty.
- Form 1040-NR for the owner, in some cases. Our 1040-NR guide lists them.
- Missed years can be corrected. If your client never filed, the catch-up guide explains the steps and the penalty abatement route.
What we deliver to you
Our service File for Your French or Swiss Accountant gives your client one file you can work from:
- the LLC's figures converted to euros or Swiss francs;
- a list of the LLC's bank accounts, so that you can decide what to declare (for example on French form 3916);
- the US filings, in the same file.
The price is fixed and quoted in writing within 48 hours. Your client signs the US forms: we prepare them, and Melya does not represent your client before the IRS.
How it works with your firm
- Your client contacts us, or you send us a short email with the situation (state of the LLC, tax years, whether returns were filed). Write to contact@melyatax.com.
- We quote a fixed price and tell you which years and forms are involved.
- Your client signs our engagement letter and answers a short online questionnaire. Documents go through our secure client portal, never by email.
- We deliver the file to your client, who passes it to you. If you want us to answer your questions directly, your client signs a separate written consent first. US rules require it before we share their information with you.
What we do not do
- We do not advise on French or Swiss tax, on the classification of the LLC at home, or on what to declare there.
- We do not keep the books of a French or Swiss company.
- We do not represent your client before the IRS.
If your client's situation looks like a case we should look at together, write to us. We answer in English or French.
Guides for your filings
Foreign-Owned US LLC Taxes: What You Must File Each Year (2026 Overview)
You own a US LLC from abroad. The yearly filings in one page: Form 5472 and pro forma 1120 for the LLC, Form 1040-NR for you in some cases, state reports, W-8 forms, and what no longer applies. With deadlines and links to each guide.
Read the guide
Form 5472: Fax Number, Mailing Address and Why You Cannot E-File It
Where to send the Form 5472 and pro forma Form 1120 of a foreign-owned single-member LLC: the IRS fax number, the dedicated Ogden mailing address, why e-filing is not allowed, how to send a Form 7004 extension, and what to keep as proof.
Read the guide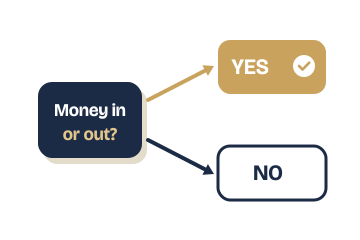
Who Must File Form 5472? The Exceptions, the Zero-Activity LLC and the "De Minimis" Myth
Does your foreign-owned US LLC have to file Form 5472? The IRS test in plain words, the six exceptions and why only one can help a single-member LLC, why there is no minimum amount, and what counts as a reportable transaction.
Read the guideThis article is general information about US tax rules for foreign-owned LLCs, not advice for your specific situation. Rules change; check the date above and ask before you file.