Schedule K-1 for a Non-Resident Partner in a US LLC: What Form 1065 Means for You
A US LLC with several members, one of them non-resident, files Form 1065 and a Schedule K-1 for each partner. What a foreign partner receives, the role of the ITIN and the W-8BEN, section 1446 withholding, and the March 15 deadline.
 Written by Amel Ouchene, IRS PTIN holderLast updated Not legal or tax advice8 min read
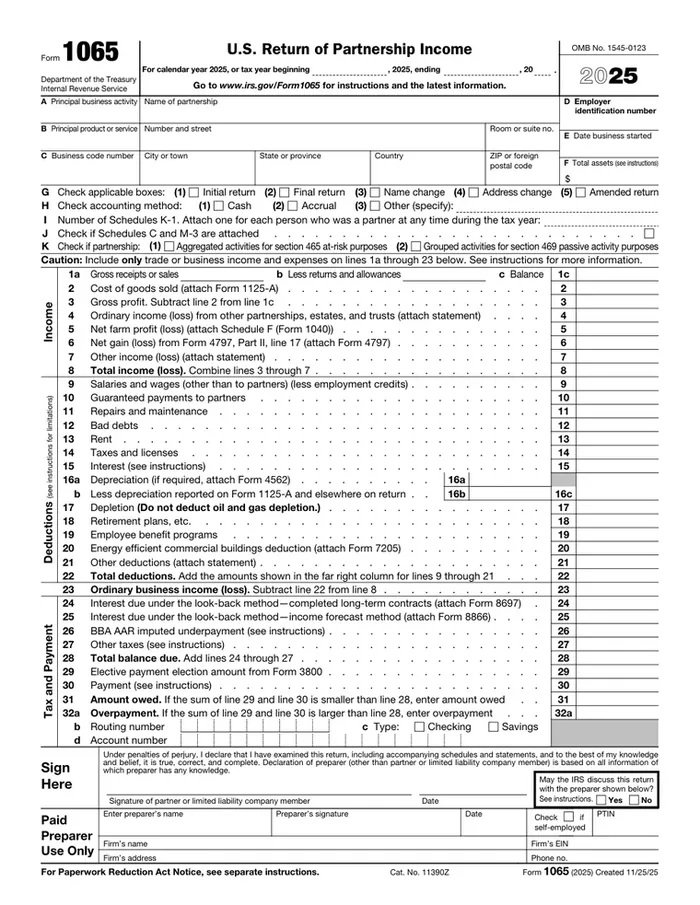
If your US LLC has two or more members and one of them is not a US resident, the LLC files Form 1065, the partnership return, and gives each partner a Schedule K-1, including the non-resident one. A foreign partner is not left out of the return. The partner is named on it, and the K-1 asks for a tax identification number.
In short:
- Default classification: a domestic LLC with two or more members is a partnership unless it filed Form 8832 to elect otherwise.
- The LLC files Form 1065 for each year it receives income or incurs a deduction or credit, and issues a Schedule K-1 per partner.
- A foreign partner is identified by a number: an SSN or ITIN for an individual, an EIN for an entity.
- Withholding may apply. If the partnership has income effectively connected with a US trade or business and has foreign partners, it may have to withhold under section 1446(a) and file Forms 8804, 8805 and 8813.
- Calendar-year due date: March 15. A Form 7004 filed by then extends the time to file, not to pay.
- Your personal US return is a separate question (Form 1040-NR), and your tax in your country of residence is outside this guide.
Why a non-resident partner changes the file, not the form
The form is the same whether the partners live in the US or abroad. The Instructions for Form 1065 say every domestic partnership must file Form 1065, unless it neither receives income nor incurs any expenditures treated as deductions or credits for federal income tax purposes. What changes with a foreign partner is a set of checks around the return: the partner's tax number, the foreign-partner question on Schedule B, and possible withholding.
For the choice between Form 1065 and Form 5472, our guide on a multi-member LLC with foreign owners explains why a multi-member LLC taxed as a partnership does not file Form 5472. If someone elected corporate status for the LLC, read the glossary entry on Form 8832 first.
What a foreign partner receives: the Schedule K-1
The Schedule K-1 is the partner's copy of that partner's share of the partnership's items for the year. The Instructions for Schedule K-1 (Form 1065) explain in Part II that Item E carries the partner's identifying number:
- Individual partner: SSN or ITIN.
- Any other partner: the partner's EIN.
- Partner that is a disregarded entity, such as a single-member LLC: the partnership enters the TIN of the beneficial owner of the entity in Item E and the owner's address in Item F.
A K-1 may show only the last four digits of the number for the partner's protection, and the instructions say the partnership has reported the complete number to the IRS.
In some cases a partner also receives Schedules K-2 and K-3, which report items with international relevance. The Instructions for Form 1065 and the separate K-2/K-3 instructions say when they are required, and we confirm this when we prepare a return. The partnership must furnish the K-1 to each partner; the instructions set a $340 penalty for each failure to furnish a Schedule K-1 (with a yearly maximum), higher when the failure is intentional.
ITIN, EIN, W-8BEN: who needs which
These three are different documents that answer different questions.
| Document | What it does | Source |
|---|---|---|
| ITIN (Form W-7) | A number for an individual partner who cannot get an SSN. It goes in Item E of the K-1. | Instructions for Form 1065; Instructions for Schedule K-1 |
| EIN | The number of a partner that is an entity (a company), entered in Item E. | Instructions for Schedule K-1, Item E |
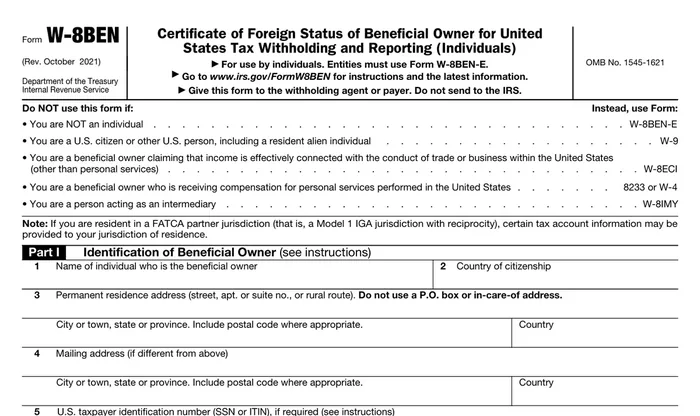
| Form W-8BEN | A certificate of foreign status that a payer or partnership may collect. | Instructions for Form W-8BEN |
The Instructions for Form 1065 say that a foreign partner without a US identifying number should be notified by the partnership of the necessity of obtaining one, and that certain aliens not eligible for an SSN can apply for an ITIN on Form W-7. Plan the W-7 process early; our ITIN glossary entry explains the basics, and our guide on getting an EIN without an SSN covers the entity side.
On the W-8BEN, the IRS instructions say that a foreign person who is a partner in a partnership and submits a Form W-8BEN for purposes of section 1441 or 1442 will generally satisfy the documentation requirements under section 1446(a) or (f) as well. They add that in some cases the documentation requirements do not match, and they refer to the section 1446 regulations. So the W-8BEN may help but does not settle everything; the partnership should confirm what it needs. Our Form W-8BEN glossary entry and the guide on Form W-8BEN-E explain which form fits which person.
Withholding on foreign partners (section 1446)
Question 14 of Schedule B asks whether the partnership had any foreign partners (for purposes of section 1446(a)) at any time during the tax year. The instructions then say that if the partnership had gross income effectively connected with a trade or business in the United States and foreign partners, it may be required to withhold tax under section 1446(a) on income allocable to foreign partners, without regard to distributions, and to file Forms 8804, 8805 and 8813. They refer to Regulations sections 1.1446-1 through -7 and to the instructions for those forms.
Two points follow from the text:
- The trigger is effectively connected income, not the mere presence of a foreign partner. Our glossary entry on effectively connected income explains the concept.
- The instructions say withholding applies on allocated income "without regard to distributions", so it can arise even when no cash leaves the LLC.
The withholding rate, the due dates for Forms 8804 and 8813, and how Form 8805 reaches the partner are not in the sources we read for this guide, so we do not state them here. The IRS instructions for Forms 8804, 8805 and 8813 are the place to check.
Section 1446(f) is a separate rule on transfers of partnership interests: the Form W-8BEN instructions say it generally requires a transferee of a partnership interest to withhold on the amount realized from a transfer by a foreign person when part of the gain would be effectively connected gain. If a partner sells or buys an interest, check this rule before closing.
The 1065 deadline and extension
The Instructions for Form 1065 say a domestic partnership must generally file by the 15th day of the 3rd month after its tax year ends; for calendar-year partnerships, the due date is March 15. If it falls on a Saturday, Sunday or legal holiday, a return filed on the next business day is timely. Form 7004 gives an automatic extension to file, generally six months per the Form 7004 instructions, and must be filed by the regular due date.
For a non-resident partner this date matters twice: the K-1 needs to reach the partner in time for their own return if they have one, and it is a month earlier than the April 15 date many foreign owners remember from other forms.
Penalties to know
The 2025 Instructions for Form 1065 set the late-filing or incomplete-return penalty at $255 for each month or part of a month (maximum 12 months), multiplied by the total number of persons who were partners during any part of the tax year. A partner who is non-resident counts like any other. Amounts are set each year, so check the instructions for the year you file.
Your own US return is a separate question
Receiving a K-1 does not by itself tell you whether you owe a personal US return. That depends on the type and source of your income. Our Form 1040-NR guide explains the test for an individual owner. What you owe in your country of residence is outside this guide; ask a local professional.
Checklist for a non-resident partner
- Confirm the LLC is taxed as a partnership (no Form 8832 corporate election).
- Give the partnership your legal name, country and address.
- Start the ITIN application if you are an individual with no SSN or ITIN.
- Ask the person preparing the return whether the LLC has effectively connected income, to see if section 1446 applies.
- Mark March 15 and decide early about Form 7004.
- Keep your K-1 with your records.
What Melya prepares
Form 1065 with Schedules K-1, K-2 and K-3: $599 for up to two partners, $99 for each additional partner. We prepare the return for your signature and confirm in writing how it is submitted before starting. The Multi-Founder Partnership bundle is $749 for two partners and adds a written 1040-NR assessment per partner. Melya is a tax preparation business whose founder holds a PTIN. We do not represent you before the IRS and do not give tax advice for your country of residence.
Related reading: Form 1042-S explained for foreign owners · Forms 8804, 8805 and 8813 explained
Frequently asked questions
Does the LLC file Form 1065 if one partner is non-resident? Yes, if the LLC is a partnership for tax purposes and has income or deductible expenses. The non-resident partner gets a Schedule K-1 like any other partner.
Does a non-resident partner need an ITIN? The K-1 asks for an SSN or ITIN for an individual partner, and the Form 1065 instructions say a foreign partner without a US number should be told to obtain one. The application is made on Form W-7.
Does a W-8BEN replace the ITIN? No. They do different jobs. A W-8BEN certifies foreign status; the ITIN is an identifying number for the K-1.
Will the LLC withhold tax on my share? It may. The instructions say a partnership with effectively connected income and foreign partners may have to withhold under section 1446(a). Whether it applies depends on the LLC's activities.
When is Form 1065 due? March 15 for a calendar-year partnership, with Form 7004 available to extend the time to file.
Does a partner in an LLC taxed as a partnership file Form 5472? Not on account of the partnership. See our guide on who must file Form 5472 for the cases where the form applies.
Sources
- IRS, Instructions for Form 1065 (2025): Who Must File, When To File, Penalties, Schedule B Question 14, foreign partners and ITIN.
- IRS, Instructions for Schedule K-1 (Form 1065): Part II, Items E and F.
- IRS, Instructions for Form W-8BEN: sections 1446(a) and (f) and partnership documentation.
- IRS, Instructions for Form 7004: automatic extension.
- IRS, About Form W-7: ITIN application.
Keep reading
Section 1446 Withholding: What a US LLC Taxed as a Partnership Owes for Its Foreign Partners
Section 1446(a) withholding explained for a US LLC with foreign partners - when it applies (effectively connected income), the 37% and 21% rates, quarterly installments, Forms 8804, 8805 and 8813, the W-8 each partner gives, and section 1446(f) on transfers.
Read the guideMulti-Member LLC With Foreign Owners: Form 1065 or Form 5472?
Your US LLC has two or more foreign owners. It files Form 1065 and a Schedule K-1 for each partner, not Form 5472, unless it elected to be taxed as a corporation. Deadlines, penalties, and the trap for partners without an SSN or ITIN.
Read the guideForms 8804, 8805 and 8813: Section 1446 Withholding for an LLC With Foreign Partners
How the three section 1446 forms work for a US LLC taxed as a partnership with foreign partners - who files Form 8804, who gets a Form 8805, when Form 8813 payments are due, who signs, where to mail them, and common mistakes.
Read the guideThis article is general information about US tax rules for foreign-owned LLCs, not advice for your specific situation. Rules change; check the date above and ask before you file.