Multi-Member LLC With Foreign Owners: Form 1065 or Form 5472?
Your US LLC has two or more foreign owners. It files Form 1065 and a Schedule K-1 for each partner, not Form 5472, unless it elected to be taxed as a corporation. Deadlines, penalties, and the trap for partners without an SSN or ITIN.
 Written by Amel Ouchene, IRS PTIN holderLast updated Not legal or tax advice9 min read
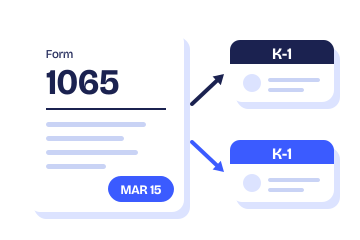
Two founders, one US LLC, nobody lives in the United States. Which form does the LLC file? Form 1065, the partnership return, with a Schedule K-1 for each owner. Form 5472 does not apply to a multi-member LLC that is taxed as a partnership. It applies only if the LLC chose to be taxed as a corporation.
In short:
- By default, a domestic LLC with two or more members is a partnership for federal tax. Unless an election is made on Form 8832, that is its classification.
- A partnership files Form 1065 every year unless it neither receives income nor has any expense treated as a deduction or credit.
- Calendar-year due date: March 15. A Form 7004 filed by that date extends the time to file.
- Late filing costs $255 per partner per month, up to 12 months (2025 instructions). The penalty is multiplied by the number of partners.
- The K-1 asks for each partner's taxpayer number. An individual partner without an SSN generally needs an ITIN to have one.
Why a multi-member LLC does not file Form 5472
The Instructions for Form 5472 define a reporting corporation as either a 25% foreign-owned U.S. corporation (which includes a foreign-owned U.S. disregarded entity) or a foreign corporation engaged in a trade or business in the United States.
A multi-member LLC taxed as a partnership is neither of these. It is not a corporation, and it is not a disregarded entity, because it has more than one owner. That is why the single-member rule you may have read about (the $25,000 penalty, the pro forma Form 1120) is about a different situation. Our guide to who must file Form 5472 covers it.
The exception: you chose corporate status. If the LLC filed Form 8832 to be taxed as a corporation, it is no longer a partnership. It then files Form 1120 each year, and Form 5472 can apply to it as a 25% foreign-owned corporation. Check whether anyone filed Form 8832 for your LLC before you decide which return you owe. See the glossary entry on Form 8832.
What a partnership return includes
- Form 1065: the partnership's income, deductions and credits for the year.
- A Schedule K-1 for each partner: each owner's share of those items. Foreign partners are identified as such on the K-1 (Item H1 asks whether the partner is domestic or foreign).
- Schedules K-2 and K-3, in the cases the Partnership Instructions for Schedules K-2 and K-3 require them. We confirm this for your LLC when we prepare the return.
In general the partnership does not pay income tax itself (see the withholding trap below for the exception to check). The K-1 carries each owner's share, and each owner then works out whether they owe a US tax return of their own. Whether a foreign partner must file a personal return depends on the kind of income and where it comes from. Our Form 1040-NR guide explains the test for an individual owner.
Deadline and extension
For a calendar-year partnership, the Form 1065 due date is March 15. If it falls on a weekend or legal holiday, the next business day counts. For the 2026 tax year, March 15, 2027 is a Monday, so no shift applies. This is a month earlier than the April 15 date many owners remember from Form 5472, so a multi-member LLC that treats April as its deadline is already late.
Form 7004 gives an automatic extension to file. It must be filed by the regular due date. It extends the time to file, not the time to pay.
Penalties
The latest published Instructions for Form 1065 (2025) set two penalties that matter here. The 2026 Form 1065 is available in draft, but the 2026 instructions are not published yet, so check the amounts again when they are:
- Late filing or incomplete return: $255 for each month or part of a month (maximum 12 months), multiplied by the number of partners during any part of the year. Two partners filing three months late: $255 × 2 × 3 = $1,530. The instructions set the amount for each year, so check the year you file.
- Failure to furnish a K-1 or a correct K-1: $340 for each Schedule K-1, with a yearly maximum that depends on gross receipts. If the failure is intentional, the amount rises.
If the partnership receives a penalty notice after filing, the instructions say it may send the IRS an explanation, and the IRS decides whether it meets the reasonable-cause criteria. No outcome is guaranteed.
The trap: partners without a taxpayer number
Item E of the Schedule K-1 asks for the partner's identifying number:
- Partner who is an individual: the SSN or the ITIN.
- Partner that is an entity: its EIN.
- Partner that is a disregarded entity (for example a single-member LLC): the partnership enters the number of the beneficial owner, the person who owns that LLC, plus that owner's address.
The instructions say a foreign partner without a US identifying number should be told by the partnership of the necessity of obtaining one. Certain people who cannot get an SSN can apply for an ITIN on Form W-7. Do not fill the field with a placeholder: a made-up number is not an identifying number. If one partner has no ITIN yet, start the W-7 process early, because the application takes time and has its own document rules. Our ITIN glossary entry explains how it works. It notes that the owner of a single-member LLC often does not need an ITIN for Form 5472; a partner named on a K-1 is a different case, because the K-1 asks for the partner's number.
Other trap: withholding on foreign partners
Question 14 of Schedule B asks whether the partnership had any foreign partners. If the partnership has income effectively connected with a US trade or business and has foreign partners, the instructions say it may be required to withhold tax under section 1446(a) on each foreign partner's share, and to file Forms 8804, 8805 and 8813. This applies even when no cash is distributed. Whether your LLC is in this situation depends on its activities, so confirm it before the first return, not after. Our glossary entry on effectively connected income explains the concept.
Paper or electronic?
The instructions require electronic filing for partnerships that file 10 or more returns of any type during the year, including information returns, and for partnerships with more than 100 partners. A small LLC will often be below both thresholds, but the count includes other returns the partnership files, so check it. The way we submit your return is confirmed in writing before any work starts. We do not promise electronic filing or IRS acceptance.
What is changing on the next forms
The return due March 15, 2027 covers tax year 2026. We compared each draft the IRS has posted with the version now in force. Status on November 6, 2026:
| Document | Status | What it means for this guide |
|---|---|---|
| Form 1065 (2026) | Draft posted (created June 23, 2026) | Schedule B question 14 (foreign partners, number of Forms 8805) and question 19 (payments made, or received and allocable to foreign partners, that require Forms 1042 and 1042-S) keep the same wording. Question 19 was widened on the 2025 form to cover payments received that are allocable to foreign partners. Other changes are renumbering and layout, the Form 4797 reference (now Part II, line 19), and the gross-receipts threshold in the business interest question ($32 million, up from $31 million). |
| Instructions for Form 1065 (2026) | Not posted yet | The deadline rule and the penalty amounts in this guide come from the 2025 instructions. Check them when the 2026 instructions appear. |
| Schedule K-1 (2026) | Draft posted | We found wording changes only (for example "current-year"). The partner identification and foreign-partner items discussed above are unchanged. |
| Instructions for Form 5472 (Rev. 12-2026) | Draft posted (October 30, 2026) | Part VII, lines 38a to 38c, are revised to reflect section 1059A (imports from related parties). Line 41a now reads "foreign-derived deduction eligible income" instead of "foreign-derived intangible income", following Public Law 119-21. The definition of a reporting corporation and the filing rule are unchanged. This matters to you only if your LLC elected corporate status. |
| Form 8832 (Rev. 12-2026) | Draft posted, replacing the December 2013 revision | Same structure: line 3 asks whether the entity has more than one owner, and lines 2a and 2b keep the 60-month limit on a new election. |
| Instructions for Form 7004 | Rev. 12-2025 is current | No newer draft posted. |
A draft is not final: the IRS says drafts of instructions usually get further changes before release. This page was last checked against the IRS drafts on November 6, 2026.
Your checklist
- Confirm the classification: no Form 8832 filed means partnership by default.
- List every partner with legal name, country, ownership percentage and tax number (SSN, ITIN or EIN).
- Start the W-7 process now for any individual partner who needs an ITIN.
- Gather the year's income and expense records for the LLC.
- Check whether any income is effectively connected with a US trade or business (section 1446 question).
- Mark March 15 and decide early whether you need Form 7004.
- For your tax in your country of residence, consult a local professional. This guide covers US federal rules only.
What Melya prepares
Form 1065 with Schedules K-1, K-2 and K-3: $599 for up to two partners, $99 for each additional partner. We prepare the return for your signature, and we confirm in writing how it is submitted before starting.
The Multi-Founder Partnership bundle is $749 for two partners. It adds a written 1040-NR assessment for each partner ($95 each), so every owner knows whether they owe a personal US return, and a calendar of your deadlines. Melya is a tax preparation business whose founder holds a PTIN. We do not represent you before the IRS and we do not give tax advice for your country of residence.
Frequently asked questions
Does a two-owner LLC with no income still file Form 1065? Not if it neither received income nor incurred any expenditure treated as a deduction or credit during the year. The instructions set that test. If your LLC had any expense that counts as a deduction, the filing duty applies, and we check this with you before anything else.
Do we file Form 5472 as well? Not for an LLC taxed as a partnership. Form 5472 applies to reporting corporations: 25% foreign-owned U.S. corporations (including foreign-owned disregarded entities) and foreign corporations engaged in a US business.
One partner is a company, not a person. Does that change anything? For a partner that is an entity, Item E of the K-1 asks for its EIN. If the partner is a single-member LLC treated as a disregarded entity, the K-1 uses the number of its owner instead.
Does the partnership itself pay US income tax? In general no: the K-1 carries each partner's share. The exception to check is section 1446 withholding on foreign partners when the partnership has income effectively connected with a US trade or business, described above.
What happens if we missed the March 15 date? File as soon as possible. The penalty grows by month and by partner, so every month counts. If you also missed other years, our guide to catching up on past years shows how to organise the work.
Sources
- IRS, Instructions for Form 1065 (2025): Who Must File, When To File, Penalties, Electronic Filing, Question 14.
- IRS, Instructions for Schedule K-1 (Form 1065): Part II, Item E.
- IRS, Instructions for Form 5472: definition of reporting corporation (Rev. 12-2024; the December 2026 draft keeps the same definition).
- IRS, Form 8832 and instructions: default classification.
- IRS, Instructions for Form 7004: automatic extension.
- IRS, About Form W-7: ITIN application.
- IRS, Draft tax forms: early-release drafts of Form 1065 (2026), Form 8832 (Rev. 12-2026) and the Instructions for Form 5472 (Rev. 12-2026).
Keep reading
Form 1099-NEC for a Foreign-Owned US LLC: Who Gets One in 2026
Your US LLC pays contractors. Do you file Form 1099-NEC? The four IRS conditions, the new $2,000 threshold, the deadline, and why a payment to a nonresident alien goes on Form 1042-S instead.
Read the guide
Lost or Forgotten EIN for Your US LLC: How to Find It
You cannot find the EIN of your US LLC. The places the IRS tells you to look, when to call the IRS, why you should not apply for a second EIN, and when you need Letter 147C instead.
Read the guideThis article is general information about US tax rules for foreign-owned LLCs, not advice for your specific situation. Rules change; check the date above and ask before you file.