Form 8832 for a Foreign-Owned US LLC: Do You Need to File It?
Does the foreign owner of a single-member US LLC have to file Form 8832? Usually not. The default classification, what the election changes, the 75-day and 12-month timing rules, who signs and where it goes.
 Written by Amel Ouchene, IRS PTIN holderLast updated Not legal or tax advice10 min read
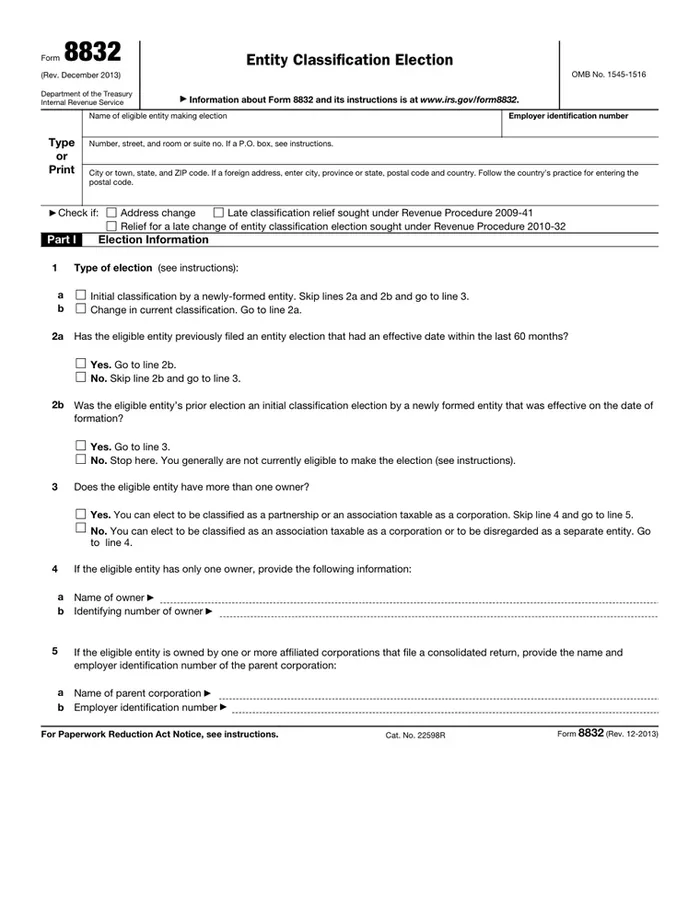
In most cases, no. A US LLC with one owner is "disregarded" by default, and an LLC with two or more owners is a partnership by default. The IRS instructions say a new eligible entity should not file Form 8832 if it will use its default classification. The form is only for an LLC that wants a classification different from its default.
In short:
- Form 8832 is an election, not a registration. It tells the IRS how an eligible entity wants to be classified: corporation, partnership, or disregarded entity.
- No election means the default: a domestic LLC with one owner is disregarded; with two or more members, a partnership.
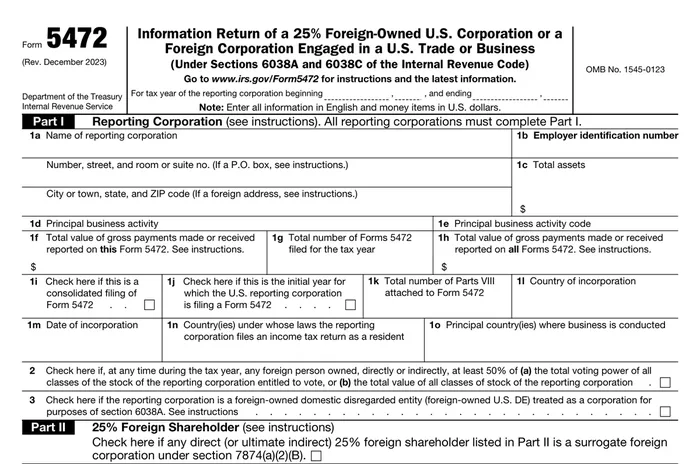
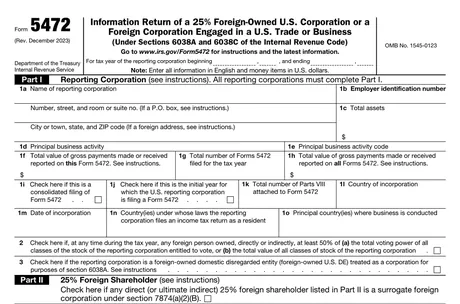
- A foreign-owned disregarded LLC does not file an income tax return of its own, but it must file Form 5472 with a pro forma Form 1120 for a year in which it has a reportable transaction with a related party.
- An LLC that elects corporate status files a full Form 1120 every year, with Form 5472 attached when it is 25% foreign owned.
- Timing: an election can take effect no more than 75 days before the filing date and no later than 12 months after it. A new election generally locks the classification for 60 months.
- Whether to elect is a decision for you and a qualified professional. This guide describes the rules; it does not recommend either path.
What Form 8832 actually is
According to the Form 8832 instructions (Rev. December 2013, the version in our reference library), an eligible entity uses the form to elect how it is classified for federal tax purposes: as a corporation, a partnership, or an entity disregarded as separate from its owner. Without a filing, the entity is classified under the default rules.
If you are looking for a short definition, our glossary entry on Form 8832 covers it in a few lines.
The default rules
The instructions state the domestic default rule in two lines. Unless an election is made on Form 8832, a domestic eligible entity is:
- A partnership if it has two or more members.
- Disregarded as an entity separate from its owner if it has a single owner.
An LLC formed under the law of a US state is a domestic entity. The separate foreign default rule in the instructions applies to entities created in a foreign jurisdiction, which is a different situation from the one described here.
What changes if the LLC stays disregarded
A disregarded entity is treated as separate from its owner for income tax purposes. The Instructions for Form 5472 explain that a foreign-owned US disregarded entity has no income tax return filing requirement of its own, but that because of the section 6038A regulations it must file a pro forma Form 1120 with Form 5472 attached, by the due date of that Form 1120 (including extensions). On the pro forma Form 1120, the only information required is the entity's name and address and items B and E on the first page. "Foreign-owned U.S. DE" is written across the top.
The same instructions set a $25,000 penalty for a reporting corporation that fails to file Form 5472 when due and in the manner prescribed. Filing a substantially incomplete form counts as a failure to file. That is why this default is not "no filing": for a foreign-owned single-member LLC with a reportable transaction in the year, it is a specific information filing. Our guide on who must file Form 5472 explains the test and the exceptions, and the pro forma Form 1120 glossary entry explains the shell return.
What changes if the LLC elects to be a corporation
The Instructions for Form 1120 say a domestic entity electing to be classified as an association taxable as a corporation must file Form 1120, and must also file Form 8832 and attach a copy to the Form 1120 for the year of the election. The same instructions say an LLC can file Form 1120 only if it has filed Form 8832 to elect to be treated as an association taxable as a corporation.
Three consequences follow from the sources:
- The return changes. The LLC files a full Form 1120, not the pro forma version. A corporation generally files by the 15th day of the 4th month after the end of its tax year, per the Instructions for Form 1120.
- Form 5472 can still apply. A reporting corporation is a 25% foreign-owned US corporation (which includes a foreign-owned US disregarded entity) or a foreign corporation engaged in a US trade or business. An LLC taxed as a corporation and owned by a foreign person fits the first category, so Form 5472 is attached to its Form 1120 under the ordinary corporate rules.
- The deemed transaction. The Form 8832 instructions say that when a disregarded entity elects to be classified as an association, its owner is treated as having contributed all of the entity's assets and liabilities to the association in exchange for stock. The instructions refer readers to Regulations section 301.7701-3(g) for the federal tax consequences. Those consequences are a matter for a qualified tax professional.
The taxation of the corporation's profit and dividends, and your position in your country of residence, are outside this guide.
Timing: the 75-day and 12-month rules
The instructions say that generally, an election specifying an entity's classification cannot take effect more than 75 days before the date it is filed, nor later than 12 months after the date it is filed. On line 8:
- If the date shown is more than 75 days before the filing date, the election defaults to 75 days before the date it is filed.
- If the date shown is more than 12 months after the filing date, the election takes effect 12 months after the date it is filed.
- If no date is entered, the election takes effect on the date filed.
Late election relief. The instructions say an entity may qualify for relief under Rev. Proc. 2009-41 if it meets each listed requirement, among them: it failed to obtain its requested classification solely because Form 8832 was not filed on time; it has reasonable cause; and three years and 75 days from the requested effective date have not passed. Part II of the form is completed for this relief and must be signed by an authorized representative of the entity and each affected person. Whether an entity meets the requirements is a fact-specific question for a professional.
The 60-month rule
According to the instructions for lines 2a and 2b, once an eligible entity elects to change its classification, it generally cannot change it again by election during the 60 months after the effective date. The IRS may, by private letter ruling, permit a change within the period if more than 50% of the ownership interests are held by persons who did not own any interest on the effective date or filing date of the prior election. The limit does not apply if the previous election was made by a newly formed entity and was effective on the date of formation.
When you do not need Form 8832
- Your LLC stays with the default. The instructions say not to file in that case.
- You want to be an S corporation. The instructions say that an entity making the section 1362(a) election files Form 2553, and an entity electing S status should not file Form 8832. An eligible entity that timely files Form 2553 and meets the other requirements is deemed to have elected association status.
- Your LLC is a partnership and stays one. It files Form 1065; see our guide to a multi-member LLC with foreign owners.
A frequent mix-up: Form 8832, Form 2553 and Form W-8BEN-E
These three forms are often confused because their numbers appear in the same searches.
| Form | What it is | Goes to |
|---|---|---|
| Form 8832 | Election of the entity's federal tax classification | The IRS service center listed in the instructions |
| Form 2553 | Election by a small business corporation to be an S corporation | The IRS |
| Form W-8BEN-E / W-8BEN | Certificate of foreign status given to a payer or platform | The payer, not the IRS |
A W-8BEN or W-8BEN-E goes to a payer, not to the IRS service center that receives Form 8832, so the two do not substitute for each other. Our guides on Form W-8BEN-E for a US LLC and on what a foreign-owned LLC files each year show how the pieces fit.
Who signs
The instructions say Form 8832 must be signed by either each member of the electing entity who is an owner at the time the election is filed, or any officer, manager or member who is authorized under local law or the organizational documents to make the election. The person signing under the second option represents under penalties of perjury that they have that authorization.
If the election is to be effective for a period before it is filed, each person who was an owner between the effective date and the filing date, and who is no longer an owner at filing, must also sign.
For a single owner, line 4 asks for the owner's name and identifying number (SSN, ITIN or EIN). The instructions say that if the owner is a foreign person or entity with no US identifying number, you enter "none" on line 4b.
Where to file
The instructions say to file Form 8832 with the IRS service center listed for your state, which is determined by where the entity's principal business, office or agency is located. The IRS has published an update that changes the mailing addresses in the printed table, so check the current address on irs.gov/form8832 or with the IRS before sending.
You must also attach a copy of Form 8832 to the entity's federal tax or information return for the tax year of the election. If the entity is not required to file a return that year, a copy must be attached to the federal tax returns of all direct or indirect owners for the tax year that includes the date the election took effect. The instructions add that failing to attach a copy does not invalidate an otherwise valid election, but penalties may be assessed against the persons required to attach it. Do not sign the copy that is attached to the return. Each member must file their return consistently with the election.
A neutral comparison
| Stay with the default (disregarded) | Elect corporate status | |
|---|---|---|
| Form 8832 | Not filed | Filed |
| Annual federal filing | Form 5472 with pro forma Form 1120 | Full Form 1120 (Form 5472 attached when 25% foreign owned) |
| Changing back | No election needed to stay | Generally blocked for 60 months |
We do not rank these options. The right choice depends on facts we do not have, including your plans, your income, and your tax position in your country of residence. Ask a qualified professional before electing.
What Melya prepares
Form 8832 Entity Classification Election: $120 (form only). If you want your LLC treated as a corporation instead of a disregarded entity, we prepare the form for your signature. The annual Form 1120 that follows an election is not included, and you generally cannot change the classification again for 60 months. Melya is a tax preparation business whose founder holds a PTIN. We do not represent you before the IRS and we do not give legal advice or tax advice for your country of residence. We do not decide whether you should elect. See the services page for the full list, or our guide on filing Form 5472 for a foreign-owned LLC if you stay with the default.
Frequently asked questions
What is a Form 8832? It is the IRS Entity Classification Election. An eligible entity, such as an LLC, uses it to choose how it is classified for federal tax purposes: corporation, partnership, or disregarded entity.
Does a single-member LLC owned by a foreigner have to file Form 8832? No. The instructions say a new eligible entity should not file it if it will use its default classification, which for a one-owner domestic LLC is "disregarded". The LLC may still have a Form 5472 and pro forma Form 1120 duty in any year with a reportable transaction.
Is Form 8832 the same as Form 2553? No. Form 2553 is the S corporation election. Form 8832 chooses among corporation, partnership and disregarded entity.
How far back can an election be made effective? Generally no more than 75 days before the filing date. Relief for a late election exists under Rev. Proc. 2009-41 in defined cases, within three years and 75 days of the requested effective date.
Can I change my mind after electing? Generally not by election during the 60 months after the effective date, with a narrow exception by private letter ruling described in the instructions.
Does the election change what I owe in my country of residence? It can have effects there. Melya does not advise on that; ask a local professional.
Sources
- IRS, Form 8832 and instructions: purpose, default rules, effect of election, when and where to file, signatures, Part II late election relief, 60-month rule.
- IRS, About Form 8832 (form and instructions): Form 2553 note, Rev. Proc. 2009-41 relief, Regulations section 301.7701-3(g) reference.
- IRS, Instructions for Form 5472: reporting corporation, foreign-owned US disregarded entity, pro forma Form 1120, $25,000 penalty.
- IRS, Instructions for Form 1120: entities electing to be taxed as corporations, LLCs, when to file.
Keep reading
After Stripe Atlas: The US Filings a Foreign Founder Still Owes Each Year
You formed a Delaware LLC or C corporation with Stripe Atlas from abroad. What you still owe each year: Form 5472 with pro forma Form 1120 or Form 1120, the Delaware annual tax or franchise tax, a registered agent, and the right W-8 or W-9 for Stripe.
Read the guide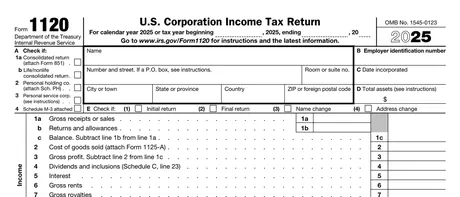
Form 5472 Checklist for 2027: Foreign-Owned LLC, Tax Year 2026
A printable checklist for filing Form 5472 and the pro forma Form 1120 for tax year 2026: who files, what to gather, which transactions to report, how to sign and send by fax or mail, the April 15, 2027 deadline and Form 7004.
Read the guideFiling Form 5472 by Fax or Mail: What Proof of Sending Exists and How to Keep It
Learn what proof exists when submitting Form 5472 by fax or mail, what a transmission report shows, and how to keep records of your filing.
Read the guideThis article is general information about US tax rules for foreign-owned LLCs, not advice for your specific situation. Rules change; check the date above and ask before you file.