Form 843 for a Form 5472 Penalty: How a Foreign-Owned LLC Requests Abatement
How a foreign-owned US LLC uses IRS Form 843 to ask for removal of a $25,000 Form 5472 penalty already assessed. When Form 843 is the right vehicle, which lines to complete, who signs, where to send it, and how it differs from a reasonable cause letter.
 Written by Amel Ouchene, IRS PTIN holderLast updated Not legal or tax advice13 min read
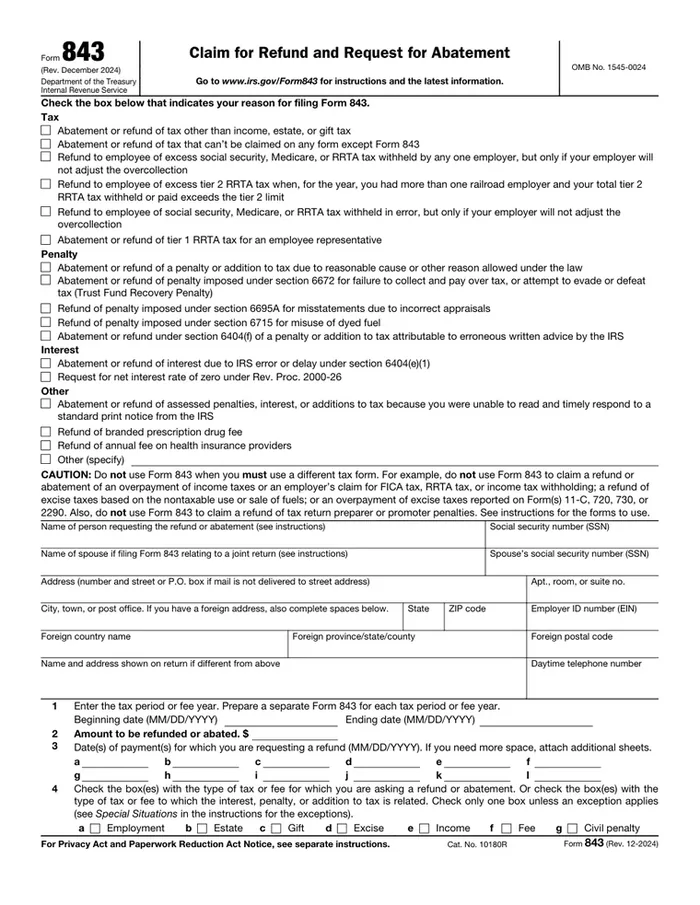
Form 843, "Claim for Refund and Request for Abatement", is the IRS form you use to ask for an assessed penalty to be removed or refunded. For a foreign-owned US LLC with a $25,000 Form 5472 penalty, you check the penalty box at the top, enter section 6038A on line 6, tick the reasonable cause box on line 7, and explain your facts on line 8 or in an attached statement. The IRS decides the outcome. Nothing in the form, and nothing Melya does, guarantees that the penalty is removed.
This guide covers the form for a Form 5472 penalty. For every other use of the form (social security tax withheld in error, interest abatement, erroneous IRS advice), see our Form 843 instructions, line by line. It does not repeat how to write the reasonable cause statement: that is in our guide to the Form 5472 penalty abatement letter.
In short:
- Form 843 is a vehicle. The reasonable cause statement is the argument. For an assessed Form 5472 penalty you normally need both: the form carries the request, the statement proves the facts.
- You do not need Form 843 if you are only attaching a statement to a late Form 5472 before any penalty is assessed. It is for a penalty the IRS has already charged (or that you have paid and want refunded).
- Use one Form 843 per tax year. Complete the penalty box, line 1 (period), line 2 (amount), line 4g, line 5, line 6 (6038A), line 7c, and line 8.
- The instructions say a corporation's Form 843 must be signed by an authorized officer, with the officer's title. A paid preparer must also sign.
- If you answer an IRS notice, the instructions say to mail the form to the return address on that notice.
- First Time Abate and the new Automatic Exemption from Penalty are separate IRS programs. Whether either applies to your LLC is the IRS's decision, not ours.
Form 843 vs a reasonable cause letter: which one, and when
People often ask whether to "file a Form 843" or "send a reasonable cause letter". These are not two competing options. They answer different questions.
| Reasonable cause statement | Form 843 | |
|---|---|---|
| What it is | The written facts and the declaration under penalties of perjury required by Treas. Reg. §1.6038A-4(b)(2)(i) | The IRS form for a claim for refund and request for abatement |
| What it does | Proves good faith and reasonable cause | Formally asks the IRS to abate (or refund) a specific penalty for a specific year |
| Needed when | Always, to win on reasonable cause | When a penalty has been assessed and you are asking for it back |
| Can stand alone? | Yes, attached to a late return or sent in reply to a notice | Line 8 has little space; the instructions allow additional sheets, so the statement is attached |
In practice, there are three situations.
- You are filing late and no penalty has been assessed yet. Attach the reasonable cause statement to each late Form 5472 and pro forma Form 1120. No Form 843 yet. Our catch-up guide walks through that filing.
- A notice arrived (for example a CP 215) or a penalty is assessed. Answer the notice. Form 843 is a clean way to do it: the Instructions for Form 843 list a penalty abatement for reasonable cause as a purpose of the form, and tell you to mail it to the return address on the notice. The IRS's own penalty relief page also says that, to request First Time Abate, you can call the number on the notice, or send a written statement or Form 843 (that page lists penalties under sections 6651, 6656, 6698 and 6699 as eligible; it does not list section 6038A, and it excludes event-based filing requirements and information reporting dependent on another filing). The notice itself is explained in our guide to IRS letters for a foreign-owned LLC.
- You already paid the penalty and want it refunded. Form 843 is the form built for this. Line 3 asks for the date of each payment.
Whether the IRS strictly requires Form 843 rather than a letter for a section 6038A penalty is something we could not confirm in the sources we hold. The regulation only requires "a written statement containing a declaration that it is made under penalties of perjury". Our approach is to send both, so the request is unambiguous and the facts are on record.
Before you start
Form 843 does not replace filing the missing returns. The IRS manual recommends that reasonable cause "not be considered for any year until all delinquent returns have been filed" (IRM 20.1.9.5.5). File Form 5472 and the pro forma Form 1120 for every missing year first. The form also warns: "Do not use Form 843 when you must use a different tax form", for example to claim an income tax overpayment.
The main lines, one by one
The form is the December 2024 revision. The line numbers below are from that form and its instructions. The choices for lines 4 and 5 follow the way our catch-up guide shows a completed form; the instructions do not give a Form 5472 example, so treat those two choices as our practice, not an IRS rule.
| Where | What to enter |
|---|---|
| Top, "Penalty" | Check "Abatement or refund of a penalty or addition to tax due to reasonable cause or other reason allowed under the law" |
| Name and EIN | The LLC's legal name and its EIN. For an entity, the instructions say to enter the EIN instead of an SSN or ITIN |
| Address | Foreign address: enter the city name on the city line only, then complete the foreign country, province and postal code lines. "Don't abbreviate the country name" |
| Line 1 | The tax period. "Prepare a separate Form 843 for each tax period" |
| Line 2 | The amount to be abated, as shown on the IRS notice. The base penalty is $25,000 for each taxable year (§1.6038A-4(a)(1)); the regulation can apply it once per related party, and continuation amounts may be added (§1.6038A-4(a)(3), (d)). Show your computation on line 8 |
| Line 3 | Dates of payments, only if you are asking for a refund of money already paid |
| Line 4 | Box g, "Civil penalty" (our practice) |
| Line 5 | Box j, "1120", because the Form 5472 of a foreign-owned LLC is attached to a pro forma Form 1120 (our practice) |
| Line 6 | The Internal Revenue Code section: 6038A. The instructions say you can generally find it on the notice of assessment |
| Line 7 | Box c, "Reasonable cause or other reason allowed under the law can be shown." If a, b and c do not apply, box d |
| Line 8 | Explain in detail why the request should be allowed and show how you computed line 2. Attach the reasonable cause statement and supporting evidence. If you add sheets, put your name and EIN on each |
Line 8 is where the case is made. "See attached reasonable cause statement" with a short summary is the usual approach. Everything you assert should be backed by a document you can attach.
Reasonable cause for a Form 5472 penalty
The ground you tick on line 7 is "reasonable cause". For this penalty the standard is in Treas. Reg. §1.6038A-4(b): a failure may be excused if "an affirmative showing is made that the taxpayer acted in good faith and there is reasonable cause". The regulation also says the exception is applied "liberally" for a small corporation (gross receipts of $20,000,000 or less) that had no knowledge of the requirements, has limited presence in and contact with the United States, and promptly and fully complies with all IRS requests. IRM 20.1.9.5.5 describes the exception the same way. The statement must be filed with the Director of the Internal Revenue Service Center where Form 5472 is required to be filed.
The regulation also links reasonable cause to the 90-day period that follows an IRS notice of failure: that period is treated as beginning no earlier than the last day on which reasonable cause existed (§1.6038A-4(b)(1)). If the failure continues more than 90 days after the notice, a further $25,000 penalty applies for each 30-day period (§1.6038A-4(d)(1)). Our reasonable cause glossary entry gives the short version, and the letter guide gives the full template.
First Time Abate and the new AEP: what we can and cannot say
Two IRS programs are often confused with a reasonable cause request.
- First Time Abate (FTA). The IRS describes it as relief for taxpayers with a history of timely compliance. For Form 5472, the manual says FTA does not apply directly to event-based filing requirements, but a penalty assessed automatically with a late pro forma Form 1120 may be abated alongside the Form 1120 failure-to-file relief if extra conditions are met (IRM 20.1.9.5.5). Details are in our First Time Abate glossary entry.
- Automatic Exemption from Penalty (AEP). In IR-2026-83 (July 8, 2026), the IRS announced AEP as replacing FTA for eligible returns with original due dates on or after January 1, 2027, starting with tax year 2025 original returns. The same release says information returns and event-driven returns generally are not eligible, and that taxpayers who do not qualify can still request relief based on reasonable cause.
We do not decide whether your LLC qualifies for either: the IRS reviews your account history, and you do not have to name FTA in your request. What we do is make sure your reasonable cause case is complete either way.
Who signs Form 843
The form's instructions are specific: "Forms 843 filed by corporations must be signed by a corporate officer authorized to sign, and the officer's title must be included with the signature." The instructions do not give an LLC example. Our reading for a foreign-owned single-member LLC is that the owner signs with a title such as "Sole member". The signature is under penalties of perjury, so only sign facts you can support.
The instructions add that "a paid tax return preparer who files Form 843 for you must sign the form and fill in the identifying information at the bottom", and must give you a copy. A preparer who does not charge should not sign. Melya charges for this service, so the paid-preparer section is signed by Melya's preparer with her PTIN. You still sign the form yourself as the taxpayer, and you send it.
You can also authorize a representative with Form 2848. Melya does not act as your representative before the IRS, so we do not use a power of attorney. We prepare the form, you review it, and you sign and send it yourself.
Where to send it, and by when
The Instructions for Form 843 give a table:
- In response to an IRS notice: "the return address from which the notice was sent".
- For penalties, or for any other reason not listed: "the service center where you would be required to file a current year tax return for the tax to which your claim or request relates".
For a foreign-owned LLC, the Form 5472 instructions give a dedicated address and fax for the pro forma Form 1120 (the IRS PIN Unit in Ogden, Utah). Whether a Form 843 with no notice should go to that same address is something we could not confirm in the sources we hold, so check the instructions for the current year or the notice. When you have a notice, use its return address.
Time limits. The instructions state a general rule for claims for refund: "within 3 years from the date you filed your original return or 2 years from the date you paid the tax, whichever is later", and refer to Publication 556. We do not interpret how this applies to a section 6038A penalty, so we cannot say whether it applies to your case. Separately, a notice has its own response deadline. Never let a notice sit.
Keep a full copy and proof of mailing or fax. See our guide to proof of filing for Form 5472.
What Melya does
Melya's Form 843 Penalty Abatement Request is quoted on request. We prepare the Form 843 for each year, assemble your reasonable cause statement and attachments list, and hand you a package ready for your review and signature. You sign and send it. We do not represent you before the IRS and do not promise any outcome: the IRS decides, and a request can be denied.
If you are still missing returns, the catch-up pack comes first. If the penalty came with a letter you cannot read, start with the IRS letters guide. If the IRS needs to confirm your EIN or name, see the 147C letter guide. If you cannot find the Reference ID printed on your forms, see what the Reference ID is. And if you want a quick read on your situation, try the penalty relief checker.
See the Form 843 Penalty Abatement Request service, from $300 per tax year
To fill in the form itself, see our Form 5472 instructions, line by line.
Official sources
- IRS, Form 843, Claim for Refund and Request for Abatement (Rev. December 2024)
- IRS, Instructions for Form 843
- Treas. Reg. §1.6038A-4, Monetary penalty (eCFR)
- IRS, IRM 20.1.9, International Penalties (20.1.9.5.5, Reasonable Cause)
- IRS, IRM 20.1.1.3.3.2.1, First Time Abate
- IRS, Administrative penalty relief
- IRS, IR-2026-83, IRS simplifies penalty relief, introduces automatic process
- IRS, Instructions for Form 5472
Frequently asked questions
What is Form 843 used for?
It is the IRS's Claim for Refund and Request for Abatement. For a foreign-owned LLC, the relevant use is asking the IRS to abate or refund a penalty "due to reasonable cause or other reason allowed under the law", such as an assessed section 6038A penalty for a missing Form 5472.
Do I need Form 843 or just a reasonable cause letter?
You need the reasonable cause statement either way. Form 843 is the form that carries the request once a penalty is assessed. Whether the IRS strictly requires the form rather than a letter for this penalty is something we could not confirm. We send both so the request is complete.
Can one Form 843 cover several years?
Generally no. The instructions say to prepare a separate Form 843 for each tax period, with exceptions that concern interest and requests for a net interest rate of zero, not this penalty.
Does Form 843 guarantee the penalty is removed?
No. The IRS decides case by case. A request can be denied.
Who must sign Form 843 for my LLC?
The instructions say a corporate officer authorized to sign, with the officer's title. For a single-member LLC we read that as the owner, signing as "Sole member" (the instructions give no LLC example). A paid preparer who prepared the form must also sign; with Melya, that is the preparer's signature and PTIN.
What if I already paid the penalty?
Form 843 is also a claim for refund. Enter the payment dates on line 3. The instructions state a general time limit for refund claims (3 years from the original return or 2 years from payment, whichever is later); we could not confirm how it applies to your penalty.
Does Melya send the form to the IRS for me?
We prepare it for your signature. You review, sign and send it. We do not represent you before the IRS.
Where do I mail Form 843 for a Form 5472 penalty?
If you are answering an IRS notice, the Instructions for Form 843 say to use "the return address from which the notice was sent". With no notice, they say to use the service center where you would file a current-year return for the tax the claim relates to. For a foreign-owned LLC, we could not confirm from the sources we hold whether that is the Ogden address used for the pro forma Form 1120, so check the current instructions or the notice, and keep proof of mailing.
Keep reading
Form 5472 Penalty Abatement Letter: How to Write the Reasonable Cause Statement (with Template)
The $25,000 Form 5472 penalty can be removed if you show reasonable cause and good faith. What the regulation actually requires, the rule that favors small foreign-owned LLCs, a fill-in template, where to send it, the First Time Abate exception, and what to do if the IRS says no.
Read the guideMissed Form 5472 for Past Years? Step-by-Step Catch-Up Guide
Missed Form 5472 filings? Discover how to catch up on late Form 5472 filing, prepare pro forma Form 1120, submit reasonable cause, and handle IRS penalties.
Read the guide
How to Read an IRS Letter About Your US LLC (Foreign Owner Guide)
How to read an IRS letter sent to a foreign-owned US LLC: where the notice number is, the deadline, the amount, and a table of the common letters (CP575, Letter 147C, CP215, CP15) with the next step for each.
Read the guideThis article is general information about US tax rules for foreign-owned LLCs, not advice for your specific situation. Rules change; check the date above and ask before you file.