Form 843 Instructions: How to Fill In the IRS Claim for Refund and Request for Abatement, Line by Line
What IRS Form 843 is for and what it cannot be used for, the box to check at the top, lines 1 to 8, who signs, where to mail it, the 3-year and 2-year time limits, and the special cases (penalty relief, social security tax withheld in error from a nonresident student, IRS error).
 Written by Amel Ouchene, IRS PTIN holderLast updated Not legal or tax advice12 min read
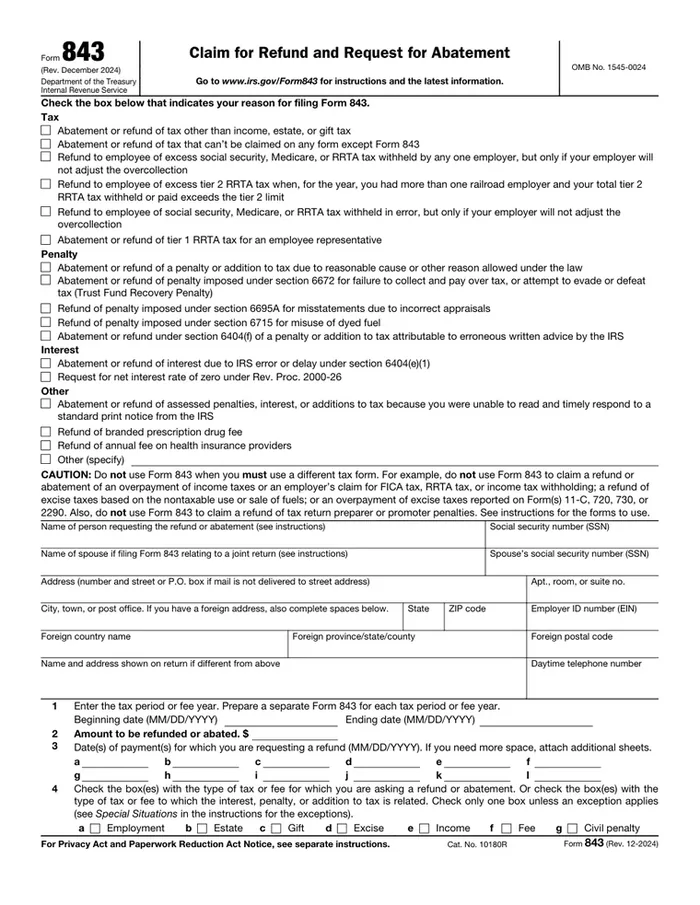
Form 843, "Claim for Refund and Request for Abatement", is the IRS form used to ask for a refund or a cancellation ("abatement") of certain taxes, penalties, additions to tax, interest and fees. You check one reason at the top, enter the period and the amount, say which tax and which penalty section it concerns, choose your reason on line 7 and explain your case on line 8. It is not a form for income tax refunds: those go on an amended return. Everything below comes from Form 843 (Rev. December 2024) and its instructions, unless another source is named.
This page covers the form for every use. If your case is a $25,000 penalty for a late Form 5472 on a foreign-owned US LLC, read our dedicated guide: Form 843 for a Form 5472 penalty.
In short:
- Use it for: penalty relief for reasonable cause, interest caused by IRS error or delay, a penalty caused by erroneous written IRS advice, social security or Medicare tax withheld in error that your employer will not repay, and some other taxes and fees.
- Do not use it for: income tax refunds (use Form 1040-X, including for a 1040-NR), an amended Form 1120 (use 1120-X), or an employer's own payroll corrections (941-X and similar).
- One form per tax period, and only one box checked at the top.
- Line 6 takes the Internal Revenue Code section of the penalty, usually printed on the IRS notice. Line 7 gives your reason: a (IRS error or delay), b (erroneous written advice), c (reasonable cause), d (none of these).
- Where to send it: in reply to a notice, to the return address on the notice. A nonresident alien claiming back social security or Medicare tax uses the address in Publication 519. Otherwise, generally the service center where you would file a current-year return for that tax (the instructions list special addresses for a few cases).
- Deadline for a refund claim: generally 3 years from the date you filed the original return or 2 years from the date you paid, whichever is later.
What Form 843 is for, and what it is not for
The instructions open with the rule: "Use Form 843 to claim a refund or request an abatement of certain taxes, penalties, additions to tax, interest, and fees." Then come the exclusions, which are the most common mistakes:
- "Do not use Form 843 to request an abatement of income, estate, or gift tax. Do not use Form 843 to request a refund of income tax or Additional Medicare Tax."
- To change an individual income tax return, including a Form 1040-NR, use Form 1040-X.
- To correct a Form 1120, use Form 1120-X.
- Employers correct payroll tax with the form matching the return filed: 941-X, 943-X, 944-X, 945-X or CT-1 X.
- Do not use it to claim a refund of agreement fees, offer-in-compromise fees or lien fees.
And one useful tip from the instructions: "If you received an IRS notice notifying you of a change to an item on your tax return, or that you owe interest, a penalty, or addition to tax, follow the instructions on the notice. You may not have to file Form 843."
The box to check at the top
The top of the form lists the reasons, grouped under Tax, Penalty, Interest and Other. "You must check one box above the name block at the top of the form to indicate your reason for filing Form 843. Do not check more than one box." The ones people use most:
| Group | Box |
|---|---|
| Tax | Refund to employee of social security, Medicare, or RRTA tax withheld in error, but only if your employer will not adjust the overcollection |
| Tax | Refund to employee of excess social security, Medicare, or RRTA tax withheld by any one employer, but only if your employer will not adjust the overcollection |
| Penalty | Abatement or refund of a penalty or addition to tax due to reasonable cause or other reason allowed under the law |
| Penalty | Abatement or refund under section 6404(f) of a penalty or addition to tax attributable to erroneous written advice by the IRS |
| Interest | Abatement or refund of interest due to IRS error or delay under section 6404(e)(1) |
| Other | Other (specify), only if no listed reason applies and no other form must be used |
Name, taxpayer number and address
- Name: the person asking for the refund or abatement. For a joint return, both spouses.
- Taxpayer number: your SSN, or your ITIN "whenever an SSN is requested". An entity, such as a partnership or corporation, enters its EIN instead.
- Foreign address: enter the city on its line and nothing else there, then complete the foreign country, province and postal code spaces. "Don't abbreviate the country name."
- If you move after filing, tell the IRS with Form 8822 (Form 8822-B for a business).
Lines 1 to 8
| Line | What to enter |
|---|---|
| 1 | The tax period (beginning and ending dates). "Prepare a separate Form 843 for each tax period or fee year" |
| 2 | The dollar amount you want refunded or abated |
| 3 | The date of each payment, only if you are asking for a refund of money already paid. Attach a sheet if needed |
| 4 | The type of tax: a Employment, b Estate, c Gift, d Excise, e Income, f Fee, g Civil penalty. For interest, a penalty or an addition to tax, check the type of tax it relates to |
| 5 | The type of return or fee it relates to: 706, 709, 940, 941, 943, 944, 945, 990-PF, 1040, 1120, 4720, CT-2, BPD fee or Other. Box i "1040" also covers the 1040-SR and the 1040-NR |
| 6 | For a penalty, the Internal Revenue Code section it is based on. "Generally, you can find the Code section on the Notice of Assessment you received from the IRS" |
| 7 | Your reason: a "Interest was assessed as a result of IRS errors or delays", b "A penalty or addition to tax was the result of erroneous written advice from the IRS", c "Reasonable cause or other reason allowed under the law can be shown", d "None of the above reasons apply" |
| 8 | "Explain in detail your reasons for filing this claim or request. Show your computation for the credit, refund, or abatement." Attach supporting evidence. Put your name and SSN, ITIN or EIN on each extra sheet |
Line 8 decides the outcome. A short summary on the form followed by "see attached statement" and a dated, signed statement with copies of the documents that prove each fact is the clearest way to present it.
Who signs
- You sign under penalties of perjury. For a joint return, both spouses sign.
- "Forms 843 filed by corporations must be signed by a corporate officer authorized to sign, and the officer's title must be included with the signature." An estate or trust signs through its fiduciary.
- Paid preparer: "A paid tax return preparer who files Form 843 for you must sign the form and fill in the identifying information at the bottom of the form", and give you a copy. Someone who prepares it for free should not sign.
- An authorized representative can file it for you only with a Form 2848 attached.
Where to mail Form 843
The instructions give a table. The lines most people need:
| You are filing | Mail it to |
|---|---|
| In response to an IRS notice | "the return address from which the notice was sent" |
| As a nonresident alien asking for a refund of social security or Medicare tax withheld in error | The address in Publication 519, following its instructions. The 2025 edition gives: Department of the Treasury, Internal Revenue Service Center, Ogden, UT 84201-0038 |
| For a net interest rate of zero | The service center where you filed your most recent return |
| For penalties, or any other reason not listed | "the service center where you would be required to file a current year tax return for the tax to which your claim or request relates" |
The table also has dedicated addresses for estate and gift tax matters, Form 8300 and certain fees. Keep a full copy and proof of mailing.
Form 843 is normally filed on paper. One exception, on the IRS page "Filing Form 843 for claims citing Kwong v. United States": certain individuals with an IRS Online Account can submit online a Form 843 for fully paid interest and penalties that cites Kwong v. United States; "at this time, only" those claims are accepted electronically. On paper, those claims go to Internal Revenue Service, 1973 N Rulon White Blvd., Ogden, UT 84201, with "Kwong vs. United States" written across the top.
Time limits
"Generally, you must file a claim for a credit or refund within 3 years from the date you filed your original return or 2 years from the date you paid the tax, whichever is later." After that, "you may no longer be entitled to a credit or refund". Publication 556 has the details. A request based on erroneous written IRS advice has its own timing rules. If you are answering a notice, the notice's own deadline also applies.
Special cases
A nonresident student or exchange visitor had social security and Medicare tax withheld in error
Publication 519 explains that nonresident aliens in F-1, J-1 or M-1 status (and, under conditions, Q status) are generally not subject to social security and Medicare tax on pay for services performed to carry out the purpose of their visa (for example on-campus work or authorized practical training), unless they are treated as resident aliens. If the tax was withheld anyway, first ask the employer to repay it. If the employer does not repay the full amount, file Form 843 with:
- a copy of your Form W-2;
- a copy of your visa;
- Form I-94 or other proof of your arrival and departure dates;
- your Form DS-2019 (J-1) or a complete copy of your Form I-20 (F-1 or M-1);
- Form I-766 if you are on optional practical training;
- if you work because of severe economic necessity, documentation showing permission to work in the United States;
- a statement from your employer on what it repaid and what it claimed, or your own statement explaining why you could not get one, or Form 8316;
- if you were exempt for only part of the year, pay statements showing the tax paid during that period.
Check the reason "Refund to employee of social security, Medicare, or RRTA tax withheld in error" at the top. Additional Medicare Tax withheld in error is not claimed on Form 843: claim it as a credit on Form 8959 with your Form 1040, 1040-SR or 1040-NR or, for a year already filed, on Form 1040-X with a corrected Form 8959.
Penalty relief for reasonable cause
Check the "reasonable cause" penalty box at the top, the tax and return type on lines 4 and 5, the Code section on line 6 (for example 6651 for failure to file a return or to pay tax, 6038A for Form 5472), box c on line 7, and make the case on line 8. As the IRS's administrative penalty relief page explains, some requests can also be made by phone or by a written statement. For a foreign-owned LLC's Form 5472 penalty, see our Form 843 guide for Form 5472 and the reasonable cause letter template.
Interest caused by IRS error or delay
The IRS can abate interest only if there was "an unreasonable error or delay in performing a managerial or ministerial act", you did not cause a significant part of it, and the interest relates to a tax for which a notice of deficiency is required (such as income tax). Interest on employment taxes cannot be abated this way. Complete lines 1 to 4, show payment dates on line 3, check box a on line 7, and on line 8 state the type of tax, when the IRS first notified you in writing, the period concerned, the circumstances, and why not abating would be "grossly unfair".
A penalty caused by erroneous written advice from the IRS
The IRS abates it only if you reasonably relied on written advice it gave in response to your specific written request, and the penalty did not come from inaccurate or incomplete information you provided. Check box b on line 7 and attach your written request, the IRS's written advice and any report identifying the penalty.
Excess social security tax withheld by one employer
If one employer withheld more than the yearly maximum and will not adjust it, attach the employer's statement (or your own, explaining why you could not get one) and your Form W-2.
How Melya helps
Melya prepares Form 843 penalty abatement requests (from $300; one form per tax year) with the reasonable cause statement, for your signature: Melya's preparer signs as paid preparer with her PTIN, you sign as the taxpayer and send it yourself. The IRS decides any relief and a request can be denied. Other uses of Form 843 (social security refunds, interest abatement) are not part of our fixed-price list. Melya does not represent clients before the IRS and does not advise on the tax rules of your country of residence. If you received a letter and are not sure what it asks, our IRS letter explained in 24 hours service ($49) tells you what it says and what to do next.
Related reading: Missed Form 5472 for past years: step-by-step catch-up · IRS letters for a foreign-owned LLC, explained
Frequently asked questions
What is Form 843 used for?
To claim a refund or request an abatement of certain taxes, penalties, additions to tax, interest and fees: for example a penalty you can show reasonable cause for, interest caused by IRS delay, or social security tax withheld in error that your employer will not repay.
Can I use Form 843 to get an income tax refund?
No. The instructions say not to use it for a refund of income tax. Individuals use Form 1040-X (also to correct a Form 1040-NR); corporations use Form 1120-X.
Where do I mail Form 843?
If you are replying to an IRS notice, to the return address on the notice. A nonresident alien claiming back social security or Medicare tax withheld in error uses the address in Publication 519. For other penalties, to the service center where you would file a current-year return for the tax concerned.
Can one Form 843 cover several years?
Generally no: one form per tax period or fee year, and per type of tax. The exceptions concern interest abatement for a single IRS act affecting several years and requests for a net interest rate of zero.
How long do I have to file Form 843?
For a refund, generally 3 years from the date you filed the original return or 2 years from the date you paid, whichever is later.
Who signs Form 843 for a corporation?
A corporate officer authorized to sign, with their title. A paid preparer who prepared it must also sign the preparer section.
Sources
- IRS, Form 843, Claim for Refund and Request for Abatement (Rev. December 2024).
- IRS, Instructions for Form 843 (Rev. December 2024): purpose, forms to use instead, who can file, where to file, separate form, time limits, lines 1 to 8, signature, paid preparer, special situations.
- IRS, Publication 519 (2025), U.S. Tax Guide for Aliens: students and exchange visitors, refund of social security and Medicare tax withheld in error, address.
- IRS, Filing Form 843 for claims citing Kwong v. United States.
- IRS, Administrative penalty relief.
- IRS, Publication 556, Examination of Returns, Appeal Rights, and Claims for Refund.
Keep reading
Form 843 for a Form 5472 Penalty: How a Foreign-Owned LLC Requests Abatement
How a foreign-owned US LLC uses IRS Form 843 to ask for removal of a $25,000 Form 5472 penalty already assessed. When Form 843 is the right vehicle, which lines to complete, who signs, where to send it, and how it differs from a reasonable cause letter.
Read the guide
Form 5472 Penalty Abatement Letter: How to Write the Reasonable Cause Statement (with Template)
The $25,000 Form 5472 penalty can be removed if you show reasonable cause and good faith. What the regulation actually requires, the rule that favors small foreign-owned LLCs, a fill-in template, where to send it, the First Time Abate exception, and what to do if the IRS says no.
Read the guideHow to Read an IRS Letter About Your US LLC (Foreign Owner Guide)
How to read an IRS letter sent to a foreign-owned US LLC: where the notice number is, the deadline, the amount, and a table of the common letters (CP575, Letter 147C, CP215, CP15) with the next step for each.
Read the guideThis article is general information about US tax rules for foreign-owned LLCs, not advice for your specific situation. Rules change; check the date above and ask before you file.